Yes, you may claim gambling losses on your federal income tax return, but the deduction is subject to strict limits. You must report all taxable gambling winnings, keep reliable records of your gambling activity and itemize deductions rather than take the standard deduction.
A major rule change applies beginning with the 2026 tax year. For 2025 returns, taxpayers can generally deduct documented gambling losses up to 100% of their reported gambling winnings. Beginning in 2026, the federal deduction is limited to 90% of gambling losses and can never exceed the gambling winnings reported for the year.
All Gambling Winnings Must Be Reported
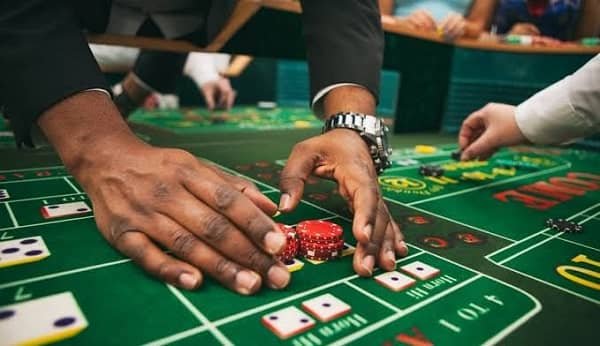
Gambling winnings are fully taxable. This includes money or prizes received from:
- Casinos and slot machines
- Sports betting
- Lotteries and raffles
- Poker tournaments
- Bingo and keno
- Horse and dog racing
- Online gambling platforms
- Sweepstakes and wagering pools
Noncash prizes are also taxable. For example, if you win a car, vacation or another valuable prize, you generally report its fair market value as gambling income.
You must report all gambling winnings even when the casino, sportsbook or other payer does not issue Form W-2G. Receiving no tax form does not make the winnings tax-free. Casual gamblers generally report gambling winnings as other income through Schedule 1 of Form 1040.
How Much Can You Deduct?
The answer depends on the tax year.
For the 2025 tax year, gambling losses may generally be deducted up to the amount of reported gambling winnings. If you reported $8,000 of winnings and had $10,000 of documented losses, the maximum deduction would be $8,000. You cannot use the additional $2,000 to reduce wages, investment income or other taxable income.
For the 2026 tax year, only 90% of gambling losses may be deductible, subject to the limit based on winnings.
Suppose you have $10,000 in gambling winnings and $10,000 in gambling losses during 2026. Ninety percent of the losses is $9,000. You may therefore report $10,000 of winnings and claim a maximum loss deduction of $9,000. This can leave $1,000 effectively subject to federal income tax even though you broke even financially.
If you won $10,000 but lost $15,000 during 2026, 90% of the losses would be $13,500. However, the deduction could not exceed the $10,000 of winnings.
You Must Itemize Your Deductions
Casual gamblers claim allowable losses as an “Other Itemized Deduction” on Schedule A of Form 1040.
You cannot claim the gambling-loss deduction while taking the standard deduction. This creates an important choice. If your standard deduction is larger than your combined itemized deductions, itemizing solely to claim gambling losses may not provide the best overall tax result.
You must still report all gambling winnings even when you take the standard deduction and receive no deduction for your losses.
For example, suppose you report $5,000 in gambling winnings but decide to take the standard deduction. You cannot subtract your losing wagers from the winnings on Schedule 1. The winnings remain reportable income.
Can You Report Only Your Net Gambling Result?
Generally, casual gamblers should not simply report the difference between annual winnings and losses as gambling income.
For example, assume you had $20,000 in winning gambling sessions and $18,000 in losing sessions. You generally report the gambling winnings and claim the allowable losses separately on Schedule A.
This distinction matters because reporting gross winnings can increase adjusted gross income. A higher AGI can affect income-based tax benefits, deductions, credits and other calculations even when gambling losses are itemized elsewhere on the return.
What Records Should You Keep?
You must be able to prove both your winnings and your losses. The IRS recommends maintaining an accurate diary or similar gambling log.
The record should generally include:
- The date of each gambling activity
- The type of wager or game
- The casino, sportsbook or gambling location
- The amounts won and lost
- Names of other people present, when relevant
Supporting documents may include wagering tickets, casino statements, canceled checks, bank records, payment-app records, credit-card statements and Forms W-2G.
Player-card statements can be useful, but they may not always show every wager or establish the complete tax result by themselves. Maintain your own records and preserve the original supporting documents.
What If You Are a Professional Gambler?
A person engaged in gambling regularly, continuously and primarily for profit may be treated as operating a gambling business rather than gambling casually. Professional gamblers generally report business activity on Schedule C.
Merely gambling frequently does not automatically make someone a professional gambler. The taxpayer’s intent, regularity, businesslike conduct, time spent and dependence on gambling income may all be relevant.
The 2026 federal change is particularly important for professional gamblers because the revised limitation applies to wagering losses and certain expenses incurred in carrying on wagering transactions. A professional gambler should consider obtaining tax advice before filing under the new rules.
Do State Tax Rules Work the Same Way?
Not necessarily. State treatment of gambling winnings and losses can differ from federal treatment. Some states allow a loss deduction, while others restrict or deny it. A taxpayer may therefore owe state income tax even when federal gambling losses substantially offset federal winnings.
The Bottom Line
You can claim gambling losses on your taxes only when you report your gambling winnings, itemize deductions and maintain evidence supporting the losses. The deduction cannot be used to create a tax loss against other income.
For 2025 returns, documented losses are generally deductible up to the amount of gambling winnings. Beginning with the 2026 tax year, only 90% of gambling losses may be deducted, with the deduction still capped at reported winnings. Because this new rule can create taxable income even for a gambler who financially broke even, accurate records are more important than ever.