Every year, many Texans make the trip west. Some visit family in Los Angeles. Others drive the Pacific Coast Highway, relocate for work, or haul freight across state lines. California’s roads are busy, fast, and often unpredictable.
If you are involved in a crash there, the rules may not match what you know from home. California handles fault, insurance, and deadlines in its own way. Understanding those differences can protect your health, your finances, and your right to compensation.
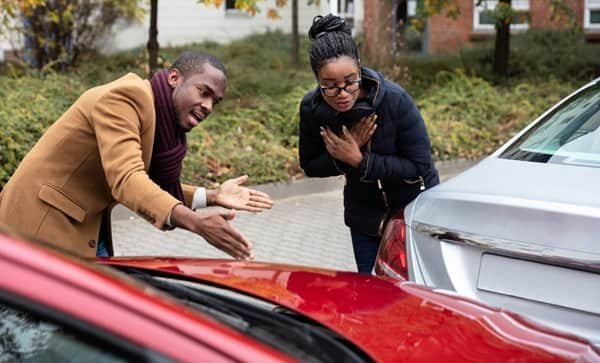
First Steps at the Scene
The moments after a collision are chaotic. Still, what you do here can shape your entire claim.
If you can safely do so:
- Check for injuries and call 911 if anyone is hurt.
- Move vehicles out of traffic when it is safe and legal.
- Exchange information with the other driver, including name, license, plate number, and insurance details.
- Take photos of vehicles, road conditions, traffic signs, and visible injuries.
- Get witness contact information before people leave.
- Avoid admitting fault, even casually. Simple apologies can be misused later.
California law requires drivers involved in accidents to stop and share information. Leaving the scene can lead to serious criminal penalties.
Report the Accident to the DMV
This step catches many drivers off guard. In California, you generally must file an SR-1 report with the DMV within 10 days if the crash:
- Caused any injury or death, or
- Resulted in property damage over $1,000
This requirement applies even if police came to the scene. It also applies regardless of who was at fault. Failing to file can lead to a suspended license.
Get Medical Care Right Away
Some injuries are obvious. Others are not. Whiplash, concussions, and internal injuries may not show symptoms for hours or even days.
See a doctor as soon as possible. Prompt treatment protects your health. It also creates a medical record linking your injuries to the crash. Insurance companies often argue that delayed treatment means the injury was minor or unrelated.
Keep copies of:
- Emergency room and doctor records
- Prescriptions and therapy bills
- Notes about pain levels and missed activities
- Records of time missed from work
California Is an At-Fault State
California follows an at-fault system. The driver who caused the crash, and their insurer, is generally responsible for paying damages.
That means you may seek compensation from the at-fault driver’s insurance for:
- Medical expenses, both current and future
- Lost wages and reduced earning ability
- Vehicle repair or replacement
- Pain and suffering
- Emotional distress
You may also use your own coverage, such as collision or uninsured motorist protection, depending on your policy.
How Shared Fault Works: A Key Difference From Texas
This is where Texans need to pay close attention.
Texas uses modified comparative fault. If you are more than 50% responsible for an accident, you generally cannot recover damages.
California uses pure comparative negligence. You can recover compensation even if you were mostly at fault. Your award is simply reduced by your share of blame.
Here is a quick example:
- Your total damages are $100,000.
- A jury finds you 70% at fault.
- In California, you could still recover $30,000.
- In Texas, you would likely recover nothing.
This rule can make a major difference. Do not assume you have no case just because you made a mistake.
Insurance Requirements and Limits
California raised its minimum auto insurance requirements starting in 2025. Drivers must now carry liability coverage of at least:
- $30,000 for injury or death to one person
- $60,000 for injury or death to more than one person
- $15,000 for property damage
You can review current rules on the California DMV’s insurance requirements page.
These minimums are often too low to cover serious injuries. That is why uninsured and underinsured motorist coverage matters. It can step in when the at-fault driver has little or no insurance.
One more important rule: under California law, uninsured drivers generally cannot recover non-economic damages like pain and suffering, even if the other driver caused the crash. Keeping valid coverage protects more than your wallet.
Watch Your Deadlines
Legal claims do not stay open forever. California sets strict time limits, known as statutes of limitations.
In general:
- Personal injury claims must be filed within two years of the accident.
- Property damage claims must be filed within three years.
- Claims against government agencies often require a formal claim within six months.
That last deadline is easy to miss. Crashes involving city buses, public vehicles, or dangerous road conditions may trigger it. Missing a deadline can end your claim permanently.
Dealing With Insurance Adjusters
Insurance adjusters may call soon after the crash. They often sound friendly and helpful. But their job is to limit what the company pays.
Protect yourself by:
- Keeping conversations brief and factual
- Declining to give recorded statements without advice
- Avoiding guesses about speed, distance, or fault
- Not signing releases or accepting quick offers too early
Early settlement offers rarely reflect the full cost of serious injuries. Once you accept, you usually cannot reopen the claim.
If you have questions about how an insurer is handling your claim, the California Department of Insurance offers consumer help and complaint options.
When to Talk to a Lawyer
Not every fender bender requires legal help. But some situations call for professional guidance, including:
- Serious or long-term injuries
- Disputes over who caused the crash
- Commercial trucks or rideshare vehicles
- Uninsured or underinsured drivers
- Claims involving government entities
- Lowball settlement offers
An experienced attorney can investigate the crash, deal with insurers, and calculate the full value of your losses. For drivers hurt in California, the Law Office of Fernando Brito Jr handles motor vehicle accident claims and can help you understand your options before key deadlines pass.
Final Thoughts
A car accident can change your life in seconds. Knowing your rights helps you take back some control.
Get medical care. Report the crash. Keep detailed records. Be careful with insurers. And remember that California’s rules may work differently from those in Texas, sometimes in your favor.
Whether you are a California resident or a Texan passing through, a little knowledge now can make a big difference later.