After a serious crash, most people assume the at-fault driver’s insurance will cover their losses. That assumption holds in many cases, but not all of them. Some drivers carry only the minimum coverage the state requires. Some carry none at all, despite the law. Others drive off before anyone can get a plate number. When that happens, the injured person’s own policy often becomes the most important source of recovery, and many people don’t know what their policy actually includes until they need it.
Massachusetts has specific rules for uninsured and underinsured motorist coverage, and those rules interact with the state’s no-fault system in ways that affect drivers, passengers, pedestrians, and motorcyclists differently.
What Every Massachusetts Policy Must Include
Massachusetts auto policies are built from several required and optional parts. The compulsory portion includes bodily injury liability, which pays for injuries the policyholder causes to others, personal injury protection, which pays up to $8,000 in medical expenses and lost wages regardless of fault, and uninsured motorist coverage. The required minimums are relatively low: $20,000 per person and $40,000 per accident for bodily injury caused by an uninsured driver.
Those amounts were set decades ago and haven’t kept pace with medical costs. A single night in a hospital, an ambulance ride, imaging, and a follow-up surgery can exceed $20,000 easily. General overviews from injury practices, such as the information at https://attorneysheehan.com/, often point out that many drivers are carrying the same minimum limits they chose when they first bought a policy, without revisiting them as their circumstances changed.
Underinsured motorist coverage is optional in Massachusetts. It applies when the at-fault driver has insurance, but not enough to cover the injured person’s damages. A policyholder can generally buy underinsured coverage up to the amount of bodily injury liability coverage they carry for others, and it is often inexpensive relative to the protection it provides.
Optional medical payments coverage is another piece worth knowing about. It can pay medical expenses beyond what PIP covers, and it is often the coverage that fills the gap while a liability or underinsured claim is still being negotiated. Because it is optional, many drivers don’t carry it, and those who do sometimes forget to make a claim under it.
Hit-and-Run Crashes
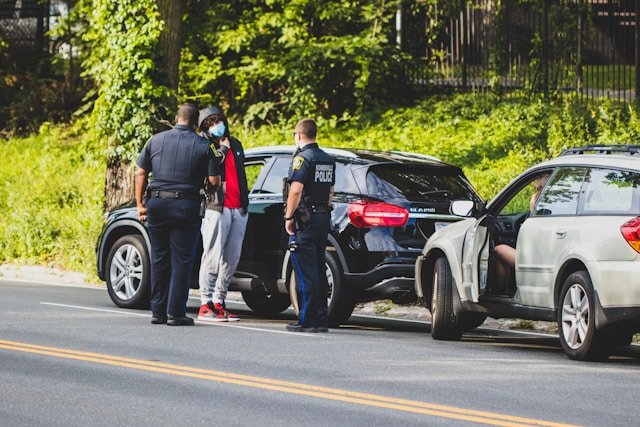
Uninsured motorist coverage usually applies to hit-and-run crashes, since the at-fault driver can’t be identified and their insurance can’t be located. That makes reporting essential. Policies typically require prompt notice to the police and the insurer, and some require evidence that another vehicle was actually involved, such as physical contact, witness statements, or video.
Funny thing is, people injured in hit-and-run crashes often delay the police report because they assume nothing will come of it. The report matters for the insurance claim regardless of whether the driver is ever found, and a late report can give the insurer a reason to question the claim.
Photographs of the damage, the location, and any debris left behind help support a hit-and-run claim. Nearby businesses and homes may have cameras that captured the other vehicle, but that footage is often overwritten within days, so asking for it quickly gives the best chance of identifying the driver.
Phantom Vehicles
Some crashes involve a driver who never touches the injured person’s car but forces it off the road, such as by cutting across lanes or running a light. These are sometimes called phantom vehicle cases. Whether uninsured coverage applies can depend on the policy language and the available evidence, so witness information and any dashcam footage become especially important.
Making an Underinsured Claim
An underinsured claim usually starts with the at-fault driver’s insurer. Once that insurer offers its full policy limits, the injured person typically needs to notify their own insurer before accepting, because the policy may require consent before settling with the other driver. Accepting the limits without following that step can, in some situations, jeopardize the underinsured claim that follows.
The injured person’s own insurer then evaluates the remaining damages, and it may dispute their value just as vigorously as the other driver’s insurer did. Here’s the kicker though: even though it’s the policyholder’s own company, the relationship in an underinsured claim can become adversarial. Someone working with a boston auto accident lawyer on that kind of claim will often find that the same medical records, wage documentation, and expert opinions used against the at-fault driver have to be presented again to their own carrier. Many policies provide for arbitration if the two sides can’t agree.
Massachusetts law also protects policyholders from unfair claim handling. Insurers that fail to make prompt, fair settlement offers when liability is reasonably clear can face additional liability under the state’s consumer protection and insurance practice statutes, which in some cases allow multiple damages and attorney’s fees.
Passengers, Pedestrians, and Household Policies
Uninsured and underinsured coverage doesn’t only protect the person driving. Passengers in a car may be able to claim under the policy covering that vehicle and, in some situations, under their own policy or a household member’s. Pedestrians and cyclists struck by an uninsured driver may also be able to make a claim through a household auto policy, even though they weren’t in a car at the time.
Speaking of households, people who don’t own a car sometimes assume they have no coverage at all. If they live with a relative who has an auto policy, they may be covered as a household member. Checking every policy in the household is one of the first steps after a serious crash involving an uninsured or underinsured driver.
Motorcyclists and Coverage Gaps
Motorcyclists face some of the largest coverage gaps on the road. Motorcycle policies in Massachusetts generally do not include the personal injury protection benefits that car policies carry, so a rider’s medical bills often go first to health insurance. Motorcycle crashes also tend to produce severe injuries, which means the at-fault driver’s minimum limits are more likely to be exhausted quickly.
For that reason, the rider’s own uninsured and underinsured coverage can be decisive. A rider who discusses a collision with a Boston motorcycle crash attorney will usually be asked for the declarations page of the motorcycle policy and of any car policy in the household, since coverage from more than one source may apply depending on the policy terms. Riders who buy only the state minimum on their bike to save money sometimes discover that the savings cost them far more after a crash.
Fault arguments can also affect motorcycle claims. Massachusetts uses a modified comparative negligence rule, which reduces recovery by the rider’s percentage of fault and bars it if the rider was more at fault than the other parties combined. Insurers sometimes lean on assumptions about riders’ behavior, which is why scene evidence and witness accounts matter.
Reviewing Coverage Before It’s Needed
Very few drivers read their declarations page closely when renewing a policy. The numbers listed there decide how much protection exists if someone else causes a crash and can’t pay for it. Raising uninsured and underinsured limits is usually one of the less expensive changes a policyholder can make, and it is one of the few that protects against other people’s decisions. A few minutes spent comparing those limits against realistic medical costs can change the outcome of a claim that hasn’t happened yet.